Doprava zdarma pre objednávky nad 59,99 € s Packetou a SPS Boxmi.

Staňte sa súčasťou komunity milovníkov kníh z celého sveta a získajte hromadu výhod.
Založiť účet zdarma
Doprava zadarmo s Packetou nad 59.99 €
Kuriér DPD 2.99 €
Kuriér GLS 3.99 €
Zberné miesto GLS 2.49 €
SPS 3.99 €
SPS Parcel Shop 2.99 €
Packeta kurýr 3.99 €
Slovenská pošta 3.99 €
Zberné miesto DPD 2.99 €
Packeta 2.99 €
 Kontakt
 Ako nakupovať

Pomoc
Doručenie
Kuriér DPD 2.99 €
Kuriér GLS 3.99 €
Zberné miesto GLS 2.49 €
SPS 3.99 €
SPS Parcel Shop 2.99 €
Packeta kurýr 3.99 €
Slovenská pošta 3.99 €
Zberné miesto DPD 2.99 €
Packeta 2.99 €
Doprava zadarmo s Packetou nad 59.99 €
Nákupný poradca
Sme tu pre Vás!
02/210 210 99
Môj účet
▸
Prázdny :-(
0
Doprava zdarma pre objednávky nad 59,99 € s Packetou a SPS Boxmi.
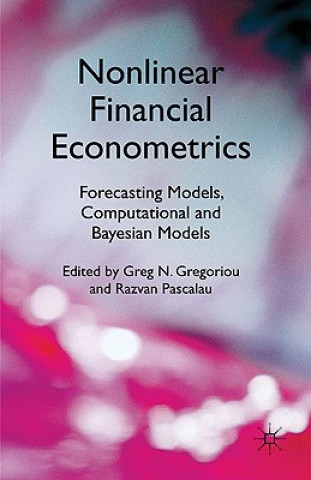
Nonlinear Financial Econometrics: Forecasting Models, Computational and Bayesian Models
Jazyk
 Angličtina
Kniha
Pevná
This book assesses several competing forecasting models for interest rates, financial returns, and r...
Celý popis
Libristo kód: 04553467
?
 136 b
136 b
55.71
€
Skladom u dodávateľa
Odosielame za 10-16 dní
Až 30 dní na vrátenie tovaru
Zákazníci tiež kúpili


 /
 Brožovaná
 21.01
€

 /
Brožovaná
58.32
€



 /
Brožovaná
67.07
€





 /
Brožovaná
19.21
€

This book assesses several competing forecasting models for interest rates, financial returns, and realized volatility. In particular, the book proposes new forecasting tools; for instance, an iterative outlier detection procedure to detect and handle outliers in models for the volatility. In addition, the book discusses in detail the construction of optimal portfolios based on out-of-sample forecasting techniques. It also addresses the effectiveness of hedging in futures markets and proposes a Bayesian framework to explain the rate spreads on corporate bonds.
Herečka
&
Polyglotka
EWA KASP
pre
Prehrať video


Libristo má najväčší výber cudzojazyčnej literatúry. Preto si knihy kupujem tu.
Informácie o knihe
Celý názov
Nonlinear Financial Econometrics: Forecasting Models, Computational and Bayesian Models
Autor
G. Gregoriou, R. Pascalau
Jazyk
Angličtina
Angličtina
Väzba
Kniha - Pevná
Dátum vydania
2010
Počet strán
195
EAN
9780230283657
ISBN
0230283659
Libristo kód
04553467
Nakladateľstvo
PALGRAVE MACMILLAN
Váha
410
Rozmery
143 x 223 x 17

Darujte túto knihu ešte dnes
Je to jednoduché
1 Pridajte knihu do košíka a vyberte možnosť doručiť ako darček 2 Obratom Vám zašleme poukaz 3 Knihu zašleme na adresu obdarovanéhoMohlo by vás tiež zaujímať

 /
Pevná
34.79
€
 /
Brožovaná
52.69
€




 /
Brožovaná
9.85
€

 /
Brožovaná
18.29
€
Knižný radca Libroamiko
Používaním tohto chatu komunikujete s generatívnou umelou inteligenciou. Jeho používaním tiež súhlasíte so spracovaním osobných údajov.
Ahoj! Som Libroamiko, tvoj knižný radca.
Ako ti môžem pomôcť?
Ahoj, som Libroamiko, môžem pomôcť?