
 Kontakt
 Ako nakupovať

Doručenie
Nákupný poradca
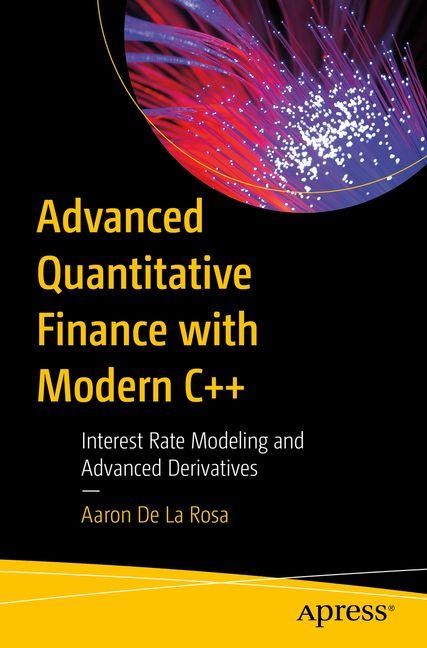
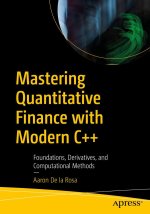
Advanced Quantitative Finance with Modern C++
 Angličtina
 161 b
Až 30 dní na vrátenie tovaru
Zákazníci tiež kúpili




 /
 Brožovaná
 13.75
€


 /
Brožovaná
14.25
€


From the elegance of the Black Scholes equation to the complexity of multi-factor interest rate models and hybrid derivatives, this book is your comprehensive guide to quantitative finance, complete with 15+ advanced C++ projects using QuantLib and Boost.
You ll move seamlessly from mathematical foundations to real-world implementation, building a professional-grade toolkit for pricing, risk analysis, and calibration. Inside, you will learn core option pricing methods, master single-and multi-factor interest rate models, and construct and calibrate trees and lattices for advanced derivatives. You will also explore cutting edge products: exotic multi-asset options, hybrid derivatives, credit instruments, and cross-currency swaps.
Packed with practical source code, step-by-step calibrations, and performance-tuned Boost integration, this book bridges the gap between academic finance and production-grade quant development. Whether you re a quant developer, financial engineer, or an advanced student, you ll gain the skills to design, implement, and deploy derivatives pricing models ready for the trading floor.
What You Will Learn
- Understand the mathematics behind Black Scholes, Vasicek, Hull White, CIR, BDT, Black Karasinski, and other core models.
- Apply finite difference schemes, trinomial trees, and Monte Carlo simulations for derivative pricing.
- Build and value swaps, swaptions, FRAs, bonds, callable/convertible debt, and multi-curve term structures.
- Implement barrier, multi-asset, hybrid, and structured products in C++.


Informácie o knihe
Angličtina

Darujte túto knihu ešte dnes
Je to jednoduché
1 Pridajte knihu do košíka a vyberte možnosť doručiť ako darček 2 Obratom Vám zašleme poukaz 3 Knihu zašleme na adresu obdarovanéhoMohlo by vás tiež zaujímať
 /
Pevná
170.52
€








Ahoj! Som Libroamiko, tvoj knižný radca.
Ako ti môžem pomôcť?